Mortgage Preapproval: How It Works, What You Need & What It Means
Mortgage preapproval is a lender’s preliminary assessment of how much you may be able to borrow for a home purchase based on information about your finances, credit, income, debts and available funds.
It can help you understand your price range before you start making offers, and sellers may view a preapproval letter as evidence that you have taken meaningful steps toward obtaining financing. But a preapproval is not a guaranteed mortgage approval.
Your loan can still change or be denied later if your financial situation changes, the property does not meet lender requirements, your documentation cannot be verified, or underwriting identifies an issue that was not known during preapproval.
This guide explains how mortgage preapproval works, what lenders may review, what documents you may need, how preapproval affects your credit, how long it may last, how it differs from prequalification, and what to avoid doing after you receive a preapproval letter.
Mortgage Preapproval: The Short Answer
Mortgage preapproval is an early lender review that estimates how much you may qualify to borrow before you have completed the full mortgage process.
The general process looks like this:
Prepare Financial Information → Compare Lenders → Submit Preapproval Information → Credit Review → Income and Asset Review → Receive Preapproval Letter → Shop for a Home → Update Information as Needed → Apply for the Property-Specific Loan
A preapproval can help you:
- understand a realistic borrowing range;
- identify potential financing problems before making an offer;
- show sellers that you have started the financing process;
- compare lenders;
- and move more efficiently when you find a home.
But the amount a lender is willing to preapprove is not necessarily the amount you should spend.
And a preapproval letter does not replace the full loan application, underwriting, appraisal, title work or final approval that comes later.
For the complete mortgage process from preparation through closing, see our step-by-step guide to how to get a mortgage.
What Is Mortgage Preapproval?
Mortgage preapproval is a preliminary lender review of your ability to qualify for a home loan.
Depending on the lender, the review may include:
- your income;
- employment;
- credit history;
- credit score;
- monthly debt obligations;
- available assets;
- down-payment funds;
- estimated purchase price;
- estimated loan amount;
- and the type of mortgage you may use.
If the lender is satisfied with the information reviewed, it may issue a preapproval letter stating that you appear qualified to borrow up to a certain amount, subject to conditions.
Those conditions matter. A preapproval letter usually depends on the financial information available at the time and may assume that:
- your income remains stable;
- your debts do not materially increase;
- your credit does not deteriorate;
- your assets remain available;
- the information you provided is accurate;
- and the property you eventually choose meets lender and loan-program requirements.
That is why preapproval should be treated as an important financing milestone, not as final loan approval.
What Does a Mortgage Preapproval Letter Mean?
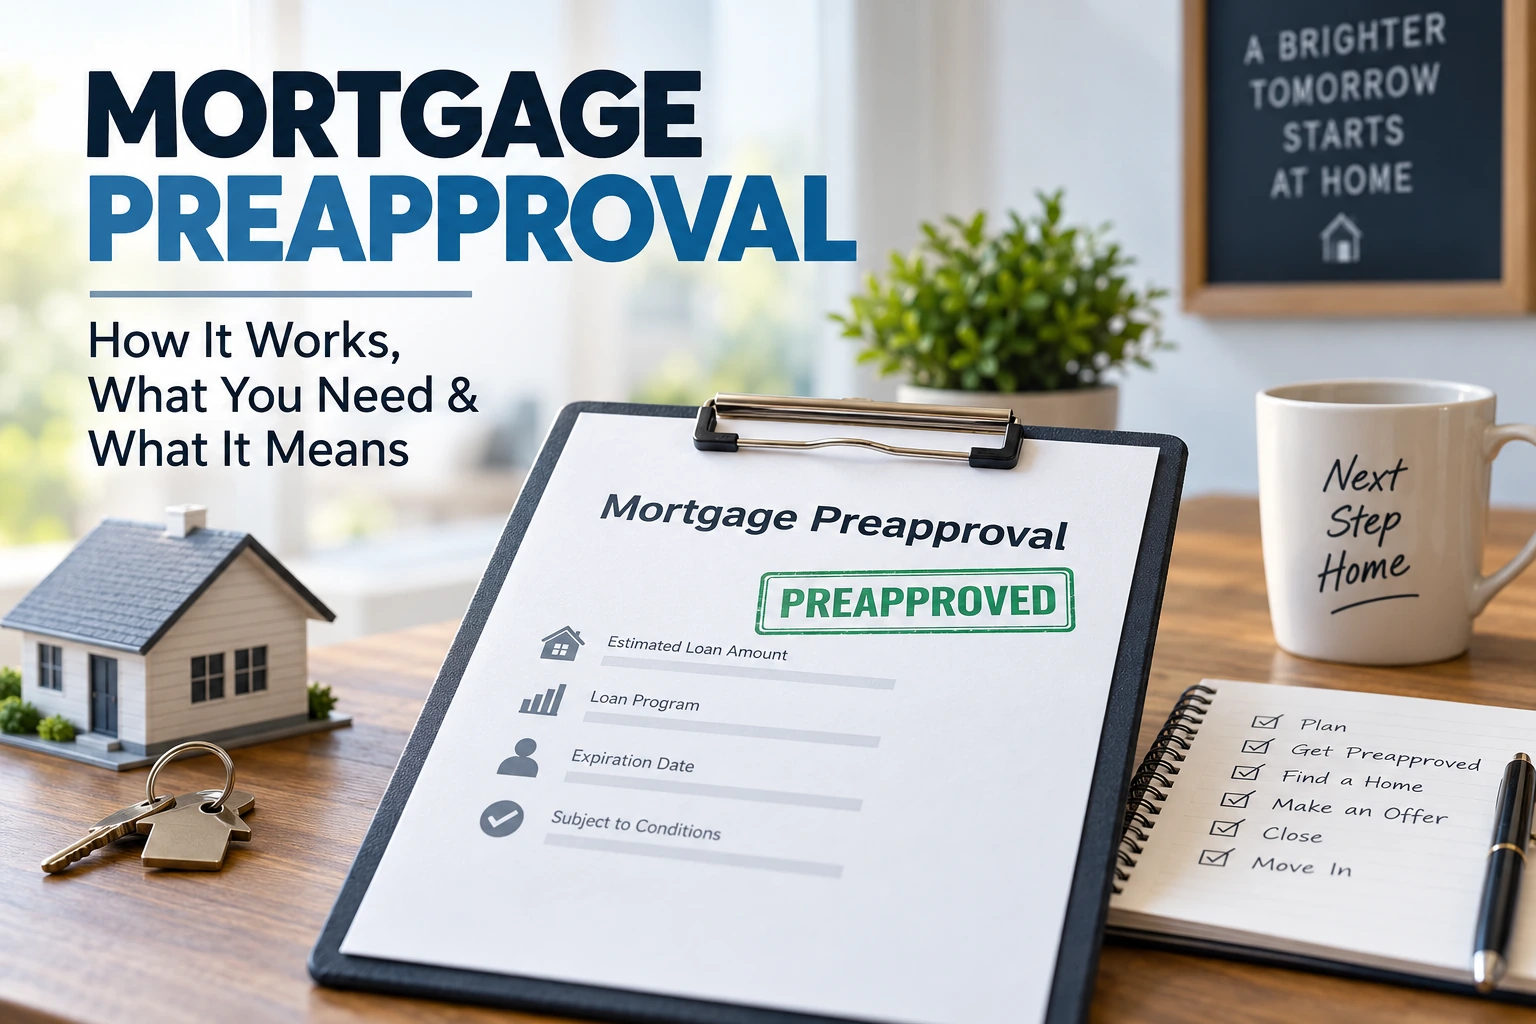
A mortgage preapproval letter generally tells you that a lender has reviewed enough of your financial information to provide a preliminary indication of how much it may be willing to lend.
A letter may include:
- the borrower’s name;
- an estimated maximum loan amount;
- an estimated purchase-price range;
- the loan type;
- an expiration date;
- conditions that still need to be satisfied;
- and contact information for the lender or loan officer.
The exact format varies by lender. A preapproval letter can be useful when you make an offer because it shows that you have already taken steps toward obtaining financing. But a preapproval is not a guaranteed mortgage approval.
The letter does not guarantee that:
- you will receive the final loan;
- you will receive the exact rate you expect;
- the property will appraise at the purchase price;
- the home will qualify for the loan program;
- your financial circumstances can change without consequence;
- or the lender will approve every property up to the amount shown.
Think of preapproval as a financial screening before the property-specific mortgage process begins.
When Should You Get Preapproved for a Mortgage?
Many buyers seek preapproval before they begin seriously shopping for homes. That timing can be useful because it gives you information before you become emotionally or financially committed to a property.
Preapproval may help you determine:
- how much a lender may be willing to finance;
- whether your current income and debt profile creates limitations;
- how much cash you may need;
- which loan programs may be relevant;
- whether credit issues should be addressed;
- and whether your target price range is realistic.
It can also make it easier to act when you find a home you want to buy.
However, you do not necessarily need to seek preapproval months before you are ready to shop. Preapproval letters can expire, and lenders may need updated documents or credit information if too much time passes.
A useful approach is to become financially prepared first, then seek preapproval when you are close enough to home shopping that the information will actually be useful.
What Do Lenders Review for Mortgage Preapproval?
The exact process varies by lender and loan program, but mortgage preapproval commonly involves a review of several broad areas.
Income
The lender wants to understand whether you have sufficient, stable income to support the proposed mortgage payment and your other obligations.
Income may come from sources such as:
- wages;
- salary;
- self-employment;
- commissions;
- bonuses;
- retirement income;
- investment income;
- or other eligible sources.
Not every source of income is treated the same way. Lenders may require documentation showing that income is stable, verifiable and expected to continue.
Employment
Employment history may be relevant because the lender needs to evaluate the reliability of the income being used to qualify you.
A recent job change does not automatically make mortgage approval impossible, but it may create additional documentation questions depending on:
- the type of employment;
- how you are paid;
- whether the new position is in the same field;
- whether income is variable;
- and the applicable loan requirements.
Credit
The lender may review your credit reports and credit scores to evaluate how you have handled debt.
Credit information can affect:
- whether you qualify;
- which loan programs may be available;
- the interest rate or pricing you are offered;
- and how much documentation or explanation may be required.
There is no single credit score that every mortgage lender or loan program requires.
Debts and Monthly Obligations
Your existing monthly debt payments can affect how much mortgage debt a lender believes you can reasonably carry.
Examples may include:
- auto loans;
- student loans;
- credit-card minimum payments;
- personal loans;
- alimony or support obligations where applicable;
- and other recurring debt.
The lender compares relevant monthly obligations with qualifying income as part of its lending calculations.
Assets and Available Funds
Lenders may also review money available for:
- your down payment;
- closing costs;
- reserves;
- and other transaction-related requirements.
Assets may include:
- checking accounts;
- savings accounts;
- investment accounts;
- retirement funds where eligible;
- documented gift funds where permitted;
- and other acceptable sources.
The lender may need to verify both the amount and the source of funds.
What Documents Do You Need for Mortgage Preapproval?
Document requirements vary by lender, borrower and loan program.
A salaried employee with straightforward finances may need different documentation from a self-employed buyer, investor or borrower with multiple income sources.
Fannie Mae’s guidance on home-loan documents illustrates the types of financial records borrowers may be asked to provide.
Commonly requested documents may include:
- recent pay stubs;
- W-2 forms;
- federal tax returns where required;
- bank statements;
- investment-account statements;
- identification;
- employment information;
- documentation of other income;
- information about current debts;
- proof of funds for the down payment or closing;
- and documentation explaining unusual financial activity when necessary.
Self-employed borrowers may be asked for additional documentation such as:
- personal tax returns;
- business tax returns;
- profit-and-loss statements;
- balance sheets;
- business bank statements;
- or other records supporting business income.
Do not assume that every lender will request the exact same documents. The safest approach is to ask the lender for a complete preapproval-document checklist and provide accurate, current information.
Mortgage Preapproval Readiness Checklist
Before applying for preapproval, review the following areas.
Credit
Ask yourself:
- Have I reviewed my credit reports recently?
- Are there errors I should dispute?
- Have I missed any recent payments?
- Am I using a large portion of my available revolving credit?
- Have I recently opened several new accounts?
Income
Confirm:
- your current income sources;
- whether income is fixed or variable;
- whether bonuses or commissions are important to qualification;
- whether you are self-employed;
- and whether recent employment changes need explanation.
Debt
List your monthly obligations, including:
- car payments;
- credit-card payments;
- student loans;
- personal loans;
- and other recurring debts.
Cash
Estimate how much money you have available for:
- down payment;
- closing costs;
- earnest money;
- inspections;
- appraisal;
- moving expenses;
- repairs;
- and emergency reserves.
Documents
Gather financial records before applying so you are not scrambling to find them after the lender asks. Being organized can make the preapproval process easier and help uncover problems earlier.
How to Get Preapproved for a Mortgage: Step by Step
1. Review Your Finances
Before contacting lenders, understand your own financial position.
Review:
- income;
- debts;
- credit;
- savings;
- down-payment funds;
- and monthly budget.
Do not use the lender’s future maximum preapproval amount as your first definition of affordability. Start with what you can comfortably manage.
2. Estimate Your Home-Buying Budget
Consider the full cost of owning the home, not just principal and interest.
Your budget may need to account for:
- mortgage principal;
- interest;
- property taxes;
- homeowners insurance;
- mortgage insurance where applicable;
- homeowners-association dues;
- utilities;
- maintenance;
- repairs;
- and other household expenses.
A lender’s qualification formula and your personal comfort level are not the same thing.
3. Compare More Than One Lender
You are not required to obtain preapproval from only one lender.
Different lenders may have:
- different loan programs;
- different qualification standards;
- different service levels;
- different documentation processes;
- and different pricing once you reach the formal loan-offer stage.
Speaking with multiple lenders can help you understand your options.
4. Submit the Requested Information
The lender may ask for information about:
- income;
- employment;
- assets;
- debts;
- credit;
- and your expected home purchase.
Provide complete and accurate information. Do not leave out debts, income changes or financial obligations because you believe they are unimportant. The lender may discover them later during underwriting.
5. Authorize the Credit Review
A lender may need to review your credit as part of the preapproval process.
Ask whether the lender will perform:
- a soft credit inquiry;
- a hard credit inquiry;
- or another type of preliminary credit review.
Practices can vary. Mortgage-shopping inquiries made within a relatively short period may be grouped for credit-scoring purposes, although the exact treatment and time window can vary by scoring model.
That is one reason it can make sense to compare lenders within a focused shopping period rather than repeatedly applying over many months.
6. Provide Documentation
Respond promptly when the lender requests documents. If something is unclear, ask what is needed and why.
Delays can occur when:
- documents are missing;
- information is inconsistent;
- statements are outdated;
- deposits cannot be explained;
- or income requires additional verification.
7. Review the Preapproval Letter
Once you receive the letter, check:
- the maximum loan amount;
- estimated purchase price if shown;
- loan type;
- expiration date;
- lender contact information;
- and any conditions.
Do not assume the highest amount shown is automatically your ideal budget.
Mortgage Preapproval vs. Prequalification
The terms preapproval and prequalification are often used as though they have fixed definitions.
In practice, lender terminology can vary.
One lender may use “prequalification” for an informal estimate based largely on information supplied by the borrower, while another may perform more verification.
Likewise, a lender may use “preapproval” for a more detailed review involving credit and documentation, but the exact process can differ.
The better comparison is therefore not simply the label.
Ask:
- Was my credit reviewed?
- Was my income documented?
- Were my assets verified?
- Were my debts reviewed?
- Did the lender evaluate actual documents?
- Is the letter based on verified information?
- Are there significant conditions?
A more thoroughly verified review may carry more practical value than a preliminary estimate, regardless of the terminology used.
Prequalification vs. Preapproval Comparison
| Question | Prequalification | Preapproval |
|---|---|---|
| Is the term used consistently by every lender? | No | No |
| May it be based partly on borrower-provided information? | Yes | Yes, depending on lender |
| May credit be reviewed? | Possibly | Commonly |
| May financial documents be reviewed? | Possibly | Commonly |
| Can it help estimate a borrowing range? | Yes | Yes |
| Does it guarantee the mortgage? | No | No |
| Should you ask exactly what the lender verified? | Yes | Yes |
The key is understanding the lender’s process rather than relying solely on the name printed at the top of the letter.
Does Mortgage Preapproval Affect Your Credit?
It can. If a lender performs a hard credit inquiry during preapproval, the inquiry may appear on your credit report and can affect your credit score.
The impact of a single mortgage inquiry is generally different from the impact of repeatedly applying for unrelated forms of credit.
Credit-scoring systems also recognize that consumers may compare mortgage lenders. That does not mean you should apply randomly or continuously.
A practical approach is to:
- prepare your finances first;
- identify a short list of lenders;
- ask what type of credit inquiry each lender uses;
- compare lenders within a focused shopping period;
- and avoid unnecessary new credit applications at the same time.
Should You Get Preapproved With Multiple Lenders?
You can. Getting information from more than one lender can help you compare:
- loan programs;
- communication;
- responsiveness;
- preliminary qualification;
- documentation requirements;
- and how each lender approaches your financial situation.
But do not confuse a preapproval with the final lender-comparison stage.
Once you have a specific property and formally apply for financing, official Loan Estimates become especially important for comparing:
- interest rates;
- points;
- lender fees;
- loan terms;
- closing-cost estimates;
- and other loan features.
A preapproval can help you identify potential lenders. It does not eliminate the need to compare the actual mortgage offers available for your property.
Does a Preapproval Lock You Into a Lender?
Generally, receiving a preapproval letter does not mean you must ultimately obtain your mortgage from that lender.
You can continue comparing lenders. However, you should understand what information each lender has reviewed and whether starting over with another lender could affect your timeline.
Once you are under contract for a home, deadlines become more important. Changing lenders late in the transaction can create risks involving:
- financing deadlines;
- appraisal timing;
- underwriting;
- document collection;
- and closing.
So while preapproval does not necessarily lock you in, lender shopping should become more deliberate once you have a signed purchase contract.
How Much Should You Borrow If You Are Preapproved for More?
Suppose a lender says you may qualify for a $450,000 mortgage. That does not mean you should automatically shop for the most expensive home that financing could support.
The lender evaluates qualification under lending standards. You live with the payment.
Before using the maximum amount, consider:
- your preferred monthly housing payment;
- taxes;
- insurance;
- homeowners-association fees;
- utilities;
- maintenance;
- repairs;
- childcare;
- transportation;
- savings goals;
- retirement contributions;
- travel;
- emergency reserves;
- and other priorities.
Preapproval Amount vs. Personal Budget
Ask these questions:
What can the lender approve? This is a lending question.
What payment fits comfortably into my life? This is a household-budget question.
How much cash will remain after closing? This is a liquidity question.
Would I still be comfortable if taxes, insurance or repairs increase? This is a risk question.
The strongest home-buying budget answers all four.
How Long Does Mortgage Preapproval Last?
Mortgage preapproval letters do not last indefinitely. Many lenders issue letters that remain valid for a limited period, often measured in weeks rather than many months.
The exact period depends on the lender. A lender may need to update your preapproval because:
- credit information becomes stale;
- pay stubs become outdated;
- bank statements become outdated;
- employment needs to be reverified;
- interest-rate conditions change;
- your debt changes;
- or the lender needs current financial information.
If your letter expires before you find a home, ask the lender what is required to refresh it. You may not need to restart the entire process, but updated documentation or another credit review may be necessary.
Preapproval Expiration and Renewal Timeline
Before the Letter Expires
Continue monitoring:
- your credit;
- employment;
- income;
- debt;
- savings;
- and home-buying timeline.
As Expiration Approaches
Ask your lender:
- when the letter expires;
- whether updated documents are required;
- whether credit will be reviewed again;
- and whether the preapproval amount could change.
After Expiration
The lender may issue an updated letter based on current information. Do not use an expired preapproval letter for a new offer without checking with the lender.
What Should You Avoid Doing After Mortgage Preapproval?
One of the most important things to understand about preapproval is that your financial profile still matters after the letter is issued.
You have not reached final approval. Avoid making major financial changes without first discussing them with your lender.
Avoid Taking On Large New Debts
Financing a new vehicle, opening a large credit account or taking out a personal loan can change your monthly obligations. That may affect qualification.
Avoid Opening Unnecessary Credit Accounts
New credit applications can affect your credit profile and may require explanation during underwriting.
Avoid Missing Payments
Continue making all debt payments on time. A new late payment can create serious problems.
Avoid Moving Large Amounts of Money Without Records
Lenders may need to verify the source of funds used in the transaction. Large unexplained deposits or transfers can create documentation questions.
Avoid Draining Your Savings
You may need money for:
- down payment;
- closing costs;
- earnest money;
- inspections;
- moving;
- repairs;
- and reserves.
Keep your overall transaction cash needs in view.
Be Careful About Employment Changes
Do not assume that changing jobs automatically destroys your preapproval.
But because employment and income are important to qualification, contact your lender before making a major employment change when possible.
Post-Preapproval Change Risk Matrix
| Change | Why It May Matter | What to Do |
|---|---|---|
| New car loan | Raises monthly debt obligations | Ask lender before financing |
| New credit card | May affect credit and available debt | Avoid unnecessary applications |
| Large purchase | Can reduce available cash or increase debt | Review cash reserves first |
| Job change | May require income/employment reevaluation | Tell lender promptly |
| Lower income | May reduce qualifying capacity | Notify lender |
| Large bank deposit | Source may need documentation | Keep records |
| Missed debt payment | Can affect credit and underwriting | Keep all accounts current |
| Using closing funds elsewhere | May reduce verified assets | Protect transaction funds |
The lender may review your finances again before closing, so financial stability matters throughout the transaction.
Can You Be Denied a Mortgage After Preapproval?
Yes. Preapproval is preliminary. Final approval generally requires the lender to evaluate both the borrower and the specific property.
A mortgage may still encounter problems if:
- income cannot be verified;
- employment changes;
- new debt is added;
- credit deteriorates;
- funds cannot be documented;
- required conditions are not satisfied;
- the appraisal creates a problem;
- the property does not meet program requirements;
- title problems arise;
- required insurance cannot be obtained;
- or underwriting identifies information that was not available during preapproval.
That does not mean preapproval is unimportant. It means preapproval and final approval serve different purposes.
Preapproval vs. Final Mortgage Approval
Preapproval
Focuses primarily on whether the borrower appears capable of qualifying based on available financial information.
Property-Specific Application
Begins once you have a specific home and formally apply for the mortgage tied to that property.
Underwriting
The lender verifies financial information, evaluates loan requirements and reviews the property-related conditions.
Final Approval
Occurs only after required conditions are satisfied and the lender is prepared to move toward closing. For the complete sequence, see our guide to getting a mortgage.
Can You Get Preapproved Before Finding a House?
Yes. That is one of the primary purposes of preapproval. The lender can evaluate your financial position before you have chosen a specific property.
The property itself is evaluated later. Once you are under contract, the lender may need:
- the signed purchase agreement;
- property details;
- appraisal;
- title information;
- insurance information;
- and other transaction-specific documents.
That is when the financing process moves beyond general borrower preapproval and becomes tied to the actual home you want to purchase.
Can Self-Employed Buyers Get Mortgage Preapproval?
Yes. Self-employed buyers can obtain mortgage preapproval, but the documentation process may be more involved. The lender may need to evaluate:
- business income;
- personal income;
- tax returns;
- length of self-employment;
- business expenses;
- recent financial performance;
- and whether income is likely to continue.
A self-employed buyer should consider gathering tax and business records early rather than waiting until after finding a property.
Complex income does not automatically prevent approval. It simply may require more documentation.
What Happens After You Get Preapproved?
Once you have a preapproval letter, the next major task is shopping for a home that fits both your financing range and your personal budget.
You can then:
- work with your real estate professional;
- evaluate homes;
- compare the total cost of ownership;
- make an offer when you find the right property;
- negotiate contract terms;
- submit the signed purchase agreement to your lender;
- move into the property-specific mortgage process;
- compare official loan terms;
- complete underwriting;
- and work toward closing.
If your offer is accepted, your deadlines can begin quickly.
Our guide to what happens after an offer is accepted on a house explains the major steps and deadlines that come next.
Mortgage Preapproval Checklist
Before applying:
- review your credit;
- list your monthly debts;
- calculate your available cash;
- estimate a comfortable housing payment;
- gather income documents;
- gather asset statements;
- identify several lenders;
- ask about credit-check procedures;
- and understand your home-shopping timeline.
When reviewing the preapproval:
- confirm the loan amount;
- confirm the estimated purchase price if shown;
- check the expiration date;
- understand the loan type;
- identify any conditions;
- ask what information was verified;
- and confirm what will need to be updated later.
After receiving the letter:
- keep making payments on time;
- avoid unnecessary new debt;
- avoid unexplained transfers;
- preserve closing funds;
- tell the lender about material financial changes;
- watch the expiration date;
- and remember that final approval still depends on underwriting and the property.
Frequently Asked Questions About Mortgage Preapproval
Do I Need Mortgage Preapproval Before Looking at Houses?
Not necessarily before viewing any home, but preapproval can be useful before you begin serious shopping. It helps establish a financing range and can make you better prepared to submit an offer.
How Long Does It Take to Get Preapproved for a Mortgage?
The timeline varies by lender and borrower. A straightforward file with complete documentation may move quickly, while complex income, credit issues or missing documents can take longer.
Ask the lender what information is required and how quickly it can review a complete file.
Does Mortgage Preapproval Guarantee a Loan?
No. Preapproval is preliminary and subject to later verification, underwriting, property review and other conditions.
Can I Be Preapproved for More Than I Should Spend?
Yes. The maximum amount a lender may approve is not necessarily the amount that best fits your household budget.
Use your own financial priorities to establish a comfortable purchase range.
Can I Get Preapproved by More Than One Lender?
Yes. Comparing lenders can help you understand available options.
Try to keep mortgage shopping organized and concentrated rather than repeatedly applying over an extended period.
Does Getting Preapproved Hurt Your Credit?
It may affect your credit if the lender performs a hard inquiry. Ask the lender what kind of credit review it uses during preapproval.
Is Preapproval the Same as Prequalification?
Not necessarily. Lender terminology varies.
Ask what information was actually reviewed and verified rather than assuming the label tells you everything.
Can I Switch Lenders After Getting Preapproved?
Generally, a preapproval does not require you to use that lender. But switching lenders after you are under contract can affect timing, so consider transaction deadlines before making a late change.
What Happens If My Preapproval Expires?
Contact the lender. It may ask for updated income, asset, employment or credit information before issuing a refreshed letter.
Can My Preapproval Amount Change?
Yes. The amount may change if:
- income changes;
- debt changes;
- credit changes;
- available funds change;
- interest-rate conditions change;
- or the lender receives new financial information.
Should I Make a Large Purchase After Preapproval?
It is usually wise to speak with your lender first. A large purchase may reduce your available cash or create new debt, either of which can affect mortgage qualification.
Before You Start House Hunting
Mortgage preapproval can give you a clearer picture of your financing options before you commit to a home.
But the most useful preapproval is not simply the letter with the highest number.
It is one that helps you understand:
- what the lender reviewed;
- how much you may qualify to borrow;
- what monthly payment fits your own budget;
- what conditions still remain;
- when the letter expires;
- and what financial changes could affect your qualification.
Use the preapproval as a planning tool, not as permission to spend the maximum amount.
Once you understand your financing position, you can shop for homes with a clearer budget and a better sense of what will be required after your offer is accepted.
For the full journey from budgeting through closing, continue with our step-by-step guide to how to buy a house.
And when you are ready to move from preapproval into the full financing process, our guide to how to get a mortgage explains the application, Loan Estimate, underwriting and closing stages.