How to Appeal a Property Tax Assessment: Steps, Evidence and Deadlines for Homeowners
A property tax appeal gives homeowners a way to challenge an assessment they believe is incorrect. But a higher tax bill, a recent home purchase, or an increase in assessed value does not, by itself, prove that an assessment is wrong. Your strongest starting point is to identify the value the assessor assigned, the date that value represents, and the local rules for disputing it.
This guide explains how to evaluate a residential property assessment, gather defensible evidence, meet the right filing requirements, and understand what happens after a protest or hearing. Procedures, deadlines, terminology, evidence rules, and tax-payment requirements differ by state and locality. Use your local assessor, assessment-review board, or other designated government authority for the rules that govern your property.
What a Property Tax Appeal Can—and Cannot—Challenge
Assessed value versus market value, taxable value and tax bill
These figures are related, but they are not interchangeable:
| Term | What it generally means | Why it matters to an appeal |
|---|---|---|
| Market value | An estimate of what the property could sell for under the applicable valuation standard and date | Comparable sales and property condition may help test the estimate |
| Assessed value | The value established for property-tax assessment under local law | Often the figure or assessment basis that can be reviewed |
| Taxable value | The amount used for taxation after applicable exemptions, limitations or adjustments | May differ from assessed value even when the assessment itself is correct |
| Tax rate | A rate imposed by the applicable taxing entities | A valuation appeal generally does not change the tax rate |
| Tax bill | The amount billed after the jurisdiction’s calculations and adjustments | Can rise even without an equivalent change in market value |
| Escrow payment | Money a mortgage servicer collects toward designated bills, often including property taxes | A servicer’s escrow calculation is a different issue from an assessor’s valuation |
The relationship is not always as simple as multiplying a property’s full market value by one tax rate. Some jurisdictions use assessment ratios, assessment limits, classifications, multiple taxing districts, or exemptions. For instance, New York State’s guidance on contesting an assessment explains how the municipality’s level of assessment can affect the comparison between assessed value and estimated market value.
A challenge should focus on a reviewable assessment issue under the applicable law, not a promised reduction in the final bill. Even a successful correction may not change taxes in proportion to the corrected value.
Is the problem your assessment, a tax rate, an exemption, or mortgage escrow?
Use this decision fork before preparing forms:
- The property appears overvalued or its records are wrong. Investigate the official assessment record and assessment-review process.
- The value seems correct, but the tax rate or levy increased. Contact the taxing body responsible for the levy; an assessor may have no authority to change rates.
- A homestead or other homeowner benefit is missing. Ask the relevant exemption administrator about a separate application or correction pathway; exemption eligibility is not the same as a valuation challenge.
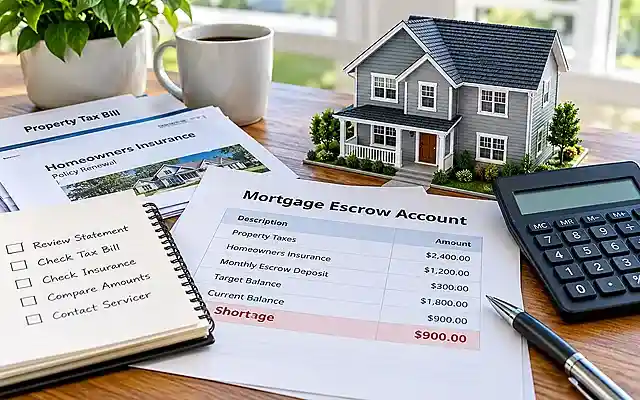
- Your mortgage payment increased after an escrow analysis. Compare the tax bill with the servicer’s escrow statement. An escrow shortage is a servicing/accounting issue, even when a property-tax change contributed to it.
The Homeownership guide explains how tax bills fit within broader homeownership costs. Do not submit a valuation appeal solely because your monthly mortgage payment changed.
First, Check Your Assessment Notice and Local Filing Deadline
Identify the assessor, valuation date, parcel and appeal authority
Find your property’s official assessment notice or online assessment record. It may be maintained by a county appraisal district, municipal assessor, property appraiser, or similar office. Record the parcel or account ID, property address, owner information, valuation or assessment date, assessment amount, property classification, and the date on the notice.
Next, identify the body that receives the actual challenge. The assessor’s office may correct an obvious record error, but a separate board, commission, or review agency may receive formal protests or grievances. Confirm the correct filing channel on an official government website or in the notice itself.
Do not assume that the tax collector, mortgage servicer, or real estate agent accepts an appeal. Also check whether the current assessment is the one open to review; prior-year corrections may require a different process or may not be available.
Why notice dates, deadlines and appeal names differ by jurisdiction
The clock may run from a mailed notice, the publication of a tentative roll, a specific statutory day, or another jurisdiction-defined event. Electronic filing and mailing rules also vary. The date you opened your notice is not necessarily the date that controls the deadline.
For example, Texas uses an appraisal-review-board protest process, while many New York municipalities use a grievance process. New York State’s grievance instructions also explain that New York City, Nassau County, and other localities have distinct filing arrangements. California uses county assessment appeals boards or equivalent local boards. None of those systems establishes a nationwide deadline.
Check the current official filing instructions immediately, even if you are still collecting evidence. Some agencies allow corrections or preliminary discussions, but an informal conversation may not preserve your right to file a formal appeal.
Decide Whether You Have Evidence for a Property Tax Appeal
An assessment appeal is more persuasive when it explains a specific, reviewable error and backs the explanation with records. Personal financial hardship or dissatisfaction with taxes may be important household concerns, but they do not automatically demonstrate an incorrect valuation.
Comparable sales: timing, location, size, condition and differences
Recent sales of genuinely similar homes can help evaluate an assessor’s estimate when comparable-sales evidence is relevant under local rules. Start with homes near your property that share important characteristics: property type, location, square footage, age, lot attributes, construction quality, condition and major features.
Use the jurisdiction’s applicable valuation date. A sale that occurred long after that date, or a listing that never closed, may be less useful or inadmissible. Confirm the jurisdiction’s evidence periods and accepted documentation before relying on a transaction.
A simple comparison worksheet could look like this. The figures are hypothetical examples, not verified transactions or appraisal adjustments:
| Home | Hypothetical sale and timing | Relevant similarity | Difference to investigate |
|---|---|---|---|
| Your home | No sale; value under review | 1,800 sq. ft.; similar neighborhood | Known roof condition; valuation-date condition |
| Comparable A | $295,000; three months before assumed valuation date | Nearby, similar size | Renovated kitchen; adjustment may be needed |
| Comparable B | $305,000; one month before assumed valuation date | Similar age and layout | Larger garage; adjustment may be needed |
| Comparable C | $287,000; two months before assumed valuation date | Similar street and lot | Smaller living area; adjustment may be needed |
The sale prices do not establish your property’s correct value on their own. Verify closed transactions, ownership interests, financing conditions, property characteristics and any permitted adjustments. If a difference cannot be supported, document the limitation rather than invent a precise dollar adjustment.
Incorrect property facts, damage or condition documentation
Review the assessor’s record for objective errors: square footage, number of bathrooms, finished basement area, building condition, improvements that do not exist, or other facts that matter under the local valuation method.
Useful records may include dated photographs, permits, floor plans, inspection findings, repair estimates, surveys or other documents permitted by the reviewing authority. A condition problem matters most when you can show what existed on the relevant valuation date and how it affected value. A repair estimate prepared later may need additional documentation to establish the earlier condition.
Appraisal reports and other locally admissible materials
A qualified independent appraisal may help in some cases, especially if the valuation issue is complicated. It may also involve a fee, and not every challenge requires one. Before spending money, ask whether the report’s effective date, appraisal approach and format would be accepted in your locality.
Texas’s official appraisal protest guidance describes property photos, sales documents, repair records and other forms of hearing evidence. Treat that list as an example of what one state recognizes, not a promise that every board accepts the same materials.
How to Appeal a Property Tax Assessment: Step by Step
1. Read the official notice and current assessment record
Verify the property and ownership identifiers, notice date, assessment year, valuation date, classification and any explanatory notes. Locate the official challenge instructions. If the document is difficult to interpret, ask the assessing agency which value is under review and which filing route applies.
2. Review public property data and build an evidence file
Compare the assessor’s property facts with documents you already have. Select relevant, verifiable comparable sales and condition evidence. Put an index on the first page of your file listing each document, what it proves, and the valuation date it relates to.
Aim for a coherent explanation: The record shows X, but documents A and B establish Y as of the applicable date. Merely attaching many photos or listings without connecting them to the asserted error may weaken clarity.
3. Check whether an informal assessor review is available
Some agencies offer a conversation, correction request or informal conference before the formal review. This may help resolve clerical mistakes or clarify the assessor’s approach. Ask directly whether the informal process changes any filing deadline; do not assume it does.
4. File the correct form or protest with the correct authority
Follow the current official form and instructions, not a template from an unrelated state. Check required supporting materials, filing fee if any, signature rules, submission methods, authorized representatives, delivery timing and receipt procedures. Keep dated copies and submission confirmations.
For example, New York State describes Form RP-524 for assessment grievances in many municipalities, with different instructions for New York City and Nassau County. A homeowner outside that system should not use the form just because it appears in an online search.
5. Prepare for a hearing, conference or board review
If your challenge proceeds to a hearing, read the notice and procedures carefully. Organize comparable properties and supporting documents so the reviewer can locate them quickly. Prepare a short summary of the assessment issue, your requested correction, and the factual basis for it.
Find out whether you can attend virtually, whether evidence must be submitted ahead of time, whether witnesses or representatives are allowed, and what happens if you miss the hearing. Evidence and submission procedures are jurisdiction-specific. In California, documents previously provided to an assessor do not automatically count as evidence at the appeals-board hearing; confirm what you must present again at your own hearing.
6. Record the decision and identify locally available further review
Retain the agency’s written decision, corrected assessment if any, and the date it was issued or served. Review whether the jurisdiction permits reconsideration, administrative appeal, arbitration, court review or another route, and whether a different deadline or payment rule applies to that next stage. Complex or court-based challenges may warrant qualified local legal advice.
Property Tax Appeal Evidence Checklist
Use this table as a working checklist, not as a universal filing requirement.
| Evidence or task | What it helps establish | What you must verify locally |
|---|---|---|
| Assessment notice and parcel record | Which property, year, value and decision are disputed | Filing trigger and allowed review year |
| Official property characteristics | Whether assessor data contains material errors | Correction route and proof standards |
| Closed comparable sales | Market evidence relative to the relevant date | Eligible sales period, selection and adjustments |
| Photos and dated repair documents | Physical condition relevant to the claimed value | Condition timing and admissibility |
| Independent appraisal, if used | A supported valuation opinion | Effective date and qualifications accepted |
| Application or protest filing receipt | Proof that the submission occurred | Method, due date and completeness |
| Hearing notice and procedures | How and when the matter will be heard | Evidence exchange, attendance and format |
| Written decision and tax bill | Result and any subsequent obligations | Further review and payment deadlines |
Appeal Readiness Worksheet
Copy this worksheet into a document or print it. Leave unknown fields blank until you confirm them on official records.
| Field | Your entry |
|---|---|
| State, county/municipality | __________________________ |
| Parcel/account ID | __________________________ |
| Current assessment year | __________________________ |
| Valuation/effective date | __________________________ |
| Noticed assessed value | __________________________ |
| Assessment ratio or limitation, if applicable | __________________________ |
| Assessor’s estimated market value, if available | __________________________ |
| Supported value or correction requested | __________________________ |
| Comparable sale 1: source, date, price, differences | __________________________ |
| Comparable sale 2: source, date, price, differences | __________________________ |
| Comparable sale 3: source, date, price, differences | __________________________ |
| Property-record mistake or condition issue | __________________________ |
| Relevant supporting documents | __________________________ |
| Official review authority and form | __________________________ |
| Exact filing deadline and receipt rule | __________________________ |
| Filing method, confirmation and date | __________________________ |
| Hearing/evidence submission requirements | __________________________ |
| Tax bill/payment obligations while pending | __________________________ |
| Decision and next-review deadline, if any | __________________________ |
| Official government page checked and date | __________________________ |
Keep property identifiers and personal records in a secure location; do not post a filled worksheet publicly.
What Happens After You File?
The office may request documents, correct a clerical issue, offer an informal review, schedule a hearing or deny the requested change. An assessor’s informal response is not always the final, appealable decision; look for the official record and next-step instructions.
An appeal is not risk-free. California’s State Board of Equalization explains that an assessment appeals board may leave the assessed value unchanged, reduce it, or increase it. Confirm the possible outcomes and governing rules with your own review authority before filing.
A value reduction, if granted, may affect a future assessment roll or generate an adjustment under local procedures. It does not necessarily lower every part of a tax bill, guarantee a refund or decide future assessment years. If the review is denied, the notice may identify remaining remedies and deadlines.
Continue monitoring property-tax payment requirements while the challenge proceeds. In California, for example, the Board of Equalization’s assessment-appeal FAQs state that property taxes remain due while an appeal is pending. Other jurisdictions may have different partial-payment or dispute procedures; obtain the controlling local rule rather than assuming that filing suspends collection.
Examples of Why Local Appeal Rules Differ
Texas: appraisal district protests and appraisal review boards
Texas’s appraisal system provides for an appraisal-review-board protest and, depending on the circumstances, other review options after the board rules. The Texas Comptroller’s official guide explains notices, informal conferences, protests, hearings and later remedies. Confirm your appraisal district’s current requirements instead of borrowing a deadline from a general guide.
New York: municipal assessment grievances
New York distinguishes an assessment check and possible informal assessor discussion from a formal grievance filed under locally applicable rules. The state’s grievance procedures identify local exceptions and direct taxpayers to verify the governing municipality and deadlines.
California: county assessment appeals
California uses a county-level appeals process involving an assessment appeals board or another authorized local board. The California State Board of Equalization directs owners to their county assessor and clerk for current forms, filing periods and available grounds for review.
These examples explain why you must obtain local instructions. They are not a three-state comparison of tax rates, nor do they establish filing rights elsewhere.
Frequently Asked Questions About Property Tax Appeals
Can I appeal because my tax bill rose?
A higher bill is a reason to investigate, not proof of an assessment error. Verify whether the change came from the assessment, applicable tax rates, exemptions, special charges or another factor. A valuation appeal may not address a rate increase.
Can I appeal if I just bought the house?
Possibly, depending on the jurisdiction, valuation rules, notice and filing window. A recent purchase price can be relevant evidence, but it is not always conclusive or measured on the correct valuation date. Check the assessor’s local procedures before relying on your closing price.
Do I need an appraisal to appeal?
Not universally. Some owners use verified sales, assessor-record corrections, condition documents or other accepted evidence. Confirm whether a professional appraisal is useful for your case and whether your review authority accepts its effective date and format.
How do I find the property tax appeal deadline in my county?
Start with the official assessment notice, assessor/appraisal district site and assessment-review body. Confirm the assessment year, triggering event, filing method and receipt requirements. If anything is unclear, contact that agency before the deadline passes.
What is the difference between a protest, grievance and appeal?
They are names used by different jurisdictions and may also refer to different stages within one jurisdiction. A Texas protest and a New York grievance are not interchangeable forms; an appeal may describe subsequent review after an initial decision.
Must I pay property taxes while my appeal is pending?
Do not assume filing pauses payment. California expressly requires timely payment during an assessment appeal. Elsewhere, payment, partial-payment and delinquency rules vary. Ask the responsible tax office or consult the applicable statute before withholding any amount.
What if my appeal is denied?
Read the written decision and immediately determine whether another administrative or judicial step exists, its deadline, fee, documentation rules and tax-payment requirements. If the next step is formal litigation, consult a qualified local professional.
Is an exemption application the same as an assessment appeal?
No. An assessment appeal generally concerns how property value or another reviewable assessment issue was determined. An exemption application asks whether a homeowner qualifies for a specific legal tax benefit. The offices, evidence and deadlines can differ.
Your Next Step: Verify the Local Process
Start with the official government assessment record for your parcel. Verify the valuation date and filing deadline, identify the reviewing authority, and write down the specific evidence-based correction you would seek. Use the Appeal Readiness Worksheet to organize the file before you submit a protest, grievance or appeal.
If the matter involves unfamiliar legal procedure, significant disputed value or court review, consider professional assistance from someone qualified under local rules. The goal is an informed, timely challenge supported by verifiable facts – not a guaranteed reduction in property taxes.