Escrow Shortage: Why Your Mortgage Payment Rose and What to Do
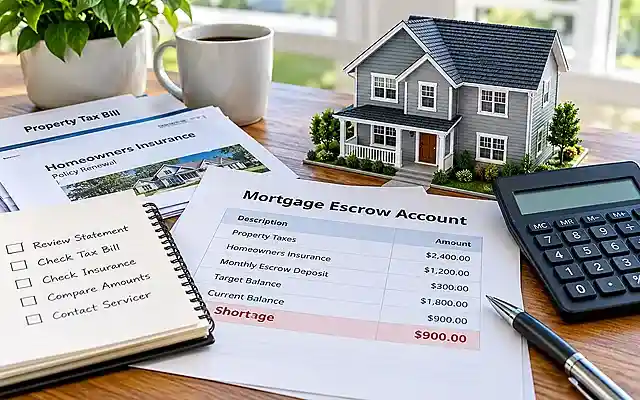
An escrow shortage occurs when the balance in your mortgage escrow account is below the target amount calculated by your loan servicer. It does not necessarily mean your escrow balance is negative. A shortage can increase your monthly mortgage bill through both a repayment amount for the past shortfall and higher deposits for future property taxes or insurance.
If your payment has increased, start with three steps: read the annual escrow analysis, separate the shortage repayment from the new ongoing escrow deposit, and compare the servicer’s tax and insurance estimates with your actual bills.
Those checks will help you identify what changed before choosing how to respond.
What Is an Escrow Shortage?
A mortgage escrow account, sometimes called an impound account, holds money collected by your loan servicer to pay specified property-related expenses.
These commonly include property taxes and homeowners insurance. The amount collected each month is based on expected bills, their payment dates, and the amount the account is allowed to retain as a reserve.
An escrow account shortage exists when the account’s balance falls below the target balance calculated during an escrow analysis. Your account can still have money in it and show a shortage because its target balance is higher.
Three terms on an escrow analysis mean different things:
- Shortage: Your current escrow balance is below the servicer’s calculated target balance at the time of analysis.
- Deficiency: Your escrow balance is negative. This is a separate regulatory category with different repayment rules.
- Surplus: Your current balance exceeds the calculated target balance.
These distinctions come from the federal Regulation X escrow account rules. They concern mortgage-servicing escrow, not earnest money or the escrow arrangements used to complete a home purchase.
Why Did My Mortgage Escrow Payment Increase?
Your monthly mortgage bill may include principal, interest, an escrow deposit and, when applicable, other charges.
Even with a fixed-rate loan, the total payment can change when the escrow portion changes. The Consumer Financial Protection Bureau’s explanation of mortgage payment increases identifies changing taxes and insurance among the possible reasons.
Common causes include:
- Higher property taxes. A change in assessed value, tax rates or applicable exemptions may affect the amount the servicer expects to pay.
- Higher insurance premiums. A homeowners insurance renewal, or another policy paid through escrow, may cost more than the servicer previously estimated.
- A mismatch between forecasts and actual bills. The account may not have collected enough in the prior period to meet its target balance.
- Payment dates and the allowed cushion. The servicer’s projection considers when bills are due and any permissible reserve, not only the annual expense total.
If the underlying property assessment appears inaccurate, consult our property tax appeal guide for the separate valuation-dispute process; an escrow calculation challenge does not itself correct an assessment.
Two different adjustments may appear on the same notice. The servicer may increase your ongoing escrow deposit to fund next year’s expected bills and separately collect installments toward a previously identified shortage.
For broader background on how mortgage payments and financing expenses fit together, see our Mortgages & Financing guide.
How to Read Your Annual Escrow Analysis Statement
Your annual escrow account statement summarizes activity during the previous escrow computation year and projects activity for the next year.
The servicer prepares that statement after performing an escrow account analysis, which uses a trial running balance to calculate target balances, future deposits, and any shortage, deficiency, or surplus.
Statement layouts vary, so focus on the amounts rather than expecting identical line-item labels from every servicer.
Use this sequence to review your notice:
- Find the computation period. Note the beginning and ending dates covered by the analysis and the effective date of any payment change.
- Compare projected and actual expenses. Look at last year’s anticipated property tax and insurance disbursements alongside the amounts actually paid.
- Review the upcoming estimates. Compare the projected taxes and insurance premiums with your current tax bill, insurance renewal and any notices of changes.
- Look at the running balance and target. Find the projected account balances, the lowest required balance, and any cushion used in the calculation.
- Identify the shortage separately. Record the stated shortage amount rather than assuming it equals the increase in annual tax or insurance costs.
- Separate your new charges. Find the ongoing monthly escrow deposit, any additional shortage repayment installment, and the revised total mortgage payment.
- Check dates and assumptions. Verify that payment dates, estimated expenses and the start of the new installment schedule match the written explanation.
Under applicable federal rules, a servicer generally may collect one-twelfth of reasonably anticipated annual escrow disbursements each month, plus amounts permitted to maintain a cushion or address a shortage or deficiency.
The maximum cushion is generally one-sixth of estimated annual disbursements, equivalent to two months of ordinary escrow deposits, but a smaller limit may apply under loan documents or state law. The rules do not require every servicer to collect the maximum cushion.
That is why a full escrow analysis can be more complicated than dividing next year’s taxes and insurance by 12. It evaluates the account as a whole and considers when individual bills must be paid.
Why Paying a Shortage May Not Restore Your Previous Payment
Paying an old shortage addresses the account’s past shortfall. It does not automatically lower the amount the servicer expects to collect for future bills.
For example, suppose the servicer projects higher property taxes and insurance premiums for the upcoming year.
Even if the previously determined shortage is fully resolved, the new ongoing monthly escrow deposit may remain higher because those bills are still expected to cost more.
Before sending additional money, ask the servicer to explain how a voluntary payment would be applied, whether it would change any scheduled shortage installments, and when a revised statement would become effective.
Do not assume an extra payment will immediately restore the old total mortgage payment.
Escrow Shortage Repayment Options Under Regulation X
These are U.S. federal mortgage-servicing rules for escrow accounts covered by Regulation X, including escrow accounts associated with federally related mortgage loans.
They do not establish a universal repayment arrangement for every loan or account. Separate exceptions to annual-statement delivery requirements can apply when a loan is more than 30 days overdue or is in foreclosure or bankruptcy.
For escrow accounts subject to the applicable federal rule, the repayment options depend partly on how the shortage compares with one month’s escrow account payment. That means the escrow portion, not your entire principal-and-interest-plus-escrow mortgage bill.
- Shortage smaller than one month’s escrow payment: The servicer may leave the shortage in place, require repayment within 30 days, or require equal monthly installments over at least 12 months.
- Shortage equal to or greater than one month’s escrow payment: The servicer may leave the shortage in place or require repayment in equal monthly installments over at least 12 months. It cannot require a lump-sum shortage repayment as the annual statement’s repayment option under this provision.
These are permitted regulatory choices, not a promise that a particular servicer must select the option you prefer. Actual servicing arrangements and applicable account rules matter.
There is also a distinction between a servicer requiring a lump sum and a homeowner voluntarily offering one. The CFPB’s mortgage servicing FAQs on escrow shortages explain that, for a shortage at least as large as one month’s escrow deposit, a servicer may accept an unsolicited voluntary lump-sum payment.
It cannot present that lump sum as a required or offered repayment option on the annual escrow statement. A separate communication about a genuinely voluntary payment may be permissible under the CFPB’s guidance.
A deficiency, meaning a negative escrow balance, has a different repayment framework. Do not apply the shortage rules automatically to a statement identifying a deficiency.
If your notice is unclear, ask the servicer which category it determined and how it calculated the amount.
Example: Reconcile Your Old and New Mortgage Payment
The following numbers are fictional. Assume principal and interest remain fixed at $1,800 a month, the simplified cushion assumption does not change, and the servicer has separately determined a $1,200 shortage through its account analysis.
Property tax estimates rise from $3,600 to $4,200 a year, while homeowners insurance estimates rise from $1,200 to $1,800 a year. Those changes raise the ongoing monthly amount for the two projected expenses from $400 to $500.
| Payment component | Before analysis | New ongoing amount | During 12-month shortage repayment |
|---|---|---|---|
| Principal and interest | $1,800 | $1,800 | $1,800 |
| Projected monthly tax and insurance escrow | $400 | $500 | $500 |
| Shortage repayment installment | $0 | $0 | $100 |
| Total monthly payment | $2,200 | $2,300 | $2,400 |
In this illustration, a permitted 12-month installment arrangement collects $1,200 ÷ 12 = $100 per month for the existing shortage. The total bill rises from $2,200 to $2,400 while that installment is collected.
Once the shortage repayment ends, the simplified payment would be $2,300, not $2,200, assuming the tax and insurance estimates and all other amounts remain unchanged. The extra $100 in ongoing escrow reflects the higher projected bills.
Important: This table is a payment illustration, not a Regulation X aggregate escrow analysis. The $1,200 shortage is an assumed result of the servicer’s separate analysis, not a number inferred from the change in annual expenses.
Real payment amounts depend on actual balances, projected bill dates, any permissible cushion, repayment terms and other loan charges.
Questions to Ask Your Mortgage Servicer
You do not need to understand every accounting line before asking for clarification. A focused list can make the conversation more useful:
- Which property tax, insurance or other escrow disbursement changed, and what source supports the new estimate?
- What were the actual disbursements in the last computation period, and what amounts are forecast for the next one?
- How did you determine the target balance, the lowest projected balance and any cushion?
- Is the amount on my notice a shortage, a deficiency or another adjustment?
- How much of my new payment is ongoing escrow, and how much is a temporary shortage repayment?
- What repayment arrangements apply to this account, and what happens if I choose to make a voluntary payment?
- On what date will the new total monthly payment begin, and when is the next escrow review expected?
- What address or approved process should I use for a written request for records or to report a suspected servicing error?
Record the date, representative or reference number, and any promise of a written explanation. If the answer depends on a tax assessment or insurance renewal, confirm those figures with the relevant issuer rather than relying only on a verbal estimate.
What if Your Escrow Statement Looks Wrong?
First, gather the annual escrow analysis, recent monthly mortgage statements, the actual property tax notices, insurance bills and any letters explaining a payment change. Compare the amounts and billing dates, then mark each discrepancy.
Contact your mortgage servicer promptly. For example, ask why the projected property tax amount differs from your current bill, why a payment appears missing, or why the shortage amount does not match the explanation you received.
The CFPB’s guidance on problems with escrow accounts explains steps consumers can take when they suspect a servicing problem.
If you need a formal written process, federal mortgage-servicing rules describe notices of error and requests for information, where applicable.
A servicer may designate a specific address for these submissions, so check the instructions on your statement or servicer website. Keep copies of the letter, documents and delivery evidence.
A disputed escrow calculation does not automatically suspend your mortgage payment obligation. Continue to follow the payment terms in force while seeking clarification, and contact the servicer immediately if the new amount is unaffordable.
If the problem remains unresolved, consider an appropriate CFPB complaint, a HUD-approved housing counselor or qualified professional assistance based on the circumstances.
Escrow Analysis Reconciliation Checklist
Use this worksheet to organize your notes before contacting the servicer. Copy the fields into a document or notebook and fill them in from your actual statement.
| Information to record | Where to check |
|---|---|
| Statement date and escrow computation period | Annual analysis heading and dates |
| Previous and new total mortgage payment | Mortgage statements and payment-change notice |
| Principal-and-interest amount | Loan payment breakdown |
| Prior deposits and actual escrow disbursements | Account transaction history |
| Current and projected property taxes | Tax bills and analysis projections |
| Current and projected insurance premiums | Policy renewal and analysis projections |
| Target low balance and cushion | Escrow analysis calculations |
| Shortage, deficiency or surplus amount | Formal account analysis |
| New ongoing monthly escrow contribution | New payment breakdown |
| Any shortage installment and start date | Repayment schedule and notice |
| Questions, responses and follow-up date | Written correspondence or call notes |
For other recurring costs to organize after a purchase, our New Homeowner Checklist offers a broader first-year recordkeeping framework.
Prepare for Future Mortgage Payment Changes
You cannot control every property tax or insurance change, but you can make the next escrow review easier to understand:
- Keep annual escrow analyses, tax notices, policy renewals and payment-change letters together.
- Check whether the new recurring payment includes a temporary shortage installment that has its own end date.
- Compare new expenses with your monthly household budget before committing extra funds to escrow.
- Set a reminder to review tax and insurance notices when they arrive, not only after your mortgage payment changes.
- If a number is unclear, write down the question, request a written breakdown and note when you will follow up.
A sudden increase can be stressful, especially when your household budget is tight. Handle the uncertainty in manageable steps: confirm the facts, separate ongoing costs from temporary catch-up payments, and contact the servicer with specific questions.
This does not remove the payment obligation, but it helps you make decisions based on verified amounts rather than assumptions.
For more on ongoing homeowner obligations beyond escrow, explore our Homeownership guide.
Frequently Asked Questions
Do I have to pay an escrow shortage immediately?
Not always. Under the applicable federal rules, a servicer’s permitted choices depend on the shortage amount relative to one month’s escrow deposit.
For a shortage at least that large, a required repayment generally must use equal monthly installments over at least 12 months if the servicer chooses to recover it, rather than demanding a lump sum through the annual statement. Confirm the terms shown on your account notice.
Will my mortgage payment drop if I pay the shortage in full?
It may decline by the temporary shortage-repayment portion if the payment is accepted and applied as expected, but the ongoing escrow deposit may stay higher if projected property taxes or insurance premiums have increased. Ask for an updated written payment breakdown rather than assuming the original total will return.
Can I have a shortage even if my escrow balance is positive?
Yes. A shortage is measured against the servicer’s calculated target balance. A positive balance can still fall below that target. A negative escrow balance is called a deficiency under Regulation X.
Why did my payment increase if my mortgage has a fixed rate?
A fixed interest rate does not freeze property taxes, homeowners insurance premiums or escrow-account adjustments. Your principal-and-interest payment may remain fixed while the escrow portion of the total amount due changes.
Your next step: Read your current escrow analysis alongside your tax and insurance bills. Identify the new ongoing escrow amount, any temporary shortage repayment, and the date the new mortgage payment takes effect. If the numbers do not reconcile, ask your servicer for a written explanation before choosing a repayment approach. A carefully verified breakdown is more useful than assuming every increase comes from the same cause.